The Timely Perspective: Should You Borrow Money to Start a Business? Mark Cuban’s Advice Sparks an Important Conversation

Helping entrepreneurs separate popular business advice from practical business decisions.

See Mark’s video here first: If you take out a loan to start a business, you’re a Moron!

Should You Borrow Money to Start a Business? Mark Cuban’s Advice Sparks an Important Conversation

Recently, billionaire entrepreneur Mark Cuban reignited debate among entrepreneurs when he made a blunt statement that quickly spread across social media.

“If you’re starting a business and you take out a loan, you’re a moron.”

Like many memorable business quotes, it attracted attention because of its boldness. But beneath the headline lies a much more important discussion, one that every entrepreneur should have before signing a loan agreement.

At The Timely Entrepreneur Resource and Research Centre, we believe Cuban’s comment deserves careful examination. Not because every entrepreneur should agree with him, but because it forces business owners to ask a critical question:

Should you borrow money before you’ve proven your business can make money?

The answer is not always straightforward.

What Was Mark Cuban Really Saying?

Contrary to what many people assumed, Cuban was not arguing that borrowing money is always a bad idea. His point was that starting a business is already filled with uncertainty. Taking on debt at the very beginning adds one certainty, the loan must still be repaid whether the business succeeds or fails – every month, the bank expects its payment, the credit union expects its payment, the finance company expects its payment, your suppliers expect their payment, your customers, however, are under no obligation to buy. That imbalance is what Cuban was highlighting. A loan does not create customers; it does not guarantee sales; it simply creates another financial obligation that the business must satisfy.

 Many aspiring entrepreneurs begin their journey with one question: “Where can I get funding?” While financing is certainly important, we often believe it has become the first question when perhaps it should be one of the last. Too often, businesses seek loans before answering more fundamental questions:

Is there genuine demand for the product or service? Have customers already shown a willingness to pay? Does the pricing cover all operating costs? How much cash will the business require each month simply to survive? What happens if sales are only half of what was projected? Without answers to these questions, borrowing money can amplify uncertainty rather than reduce it.

Money Does Not Solve Every Business Problem

One of the biggest misconceptions among new entrepreneurs is that a lack of money is the primary reason businesses fail. In reality, many businesses struggle for reasons that additional funding alone cannot fix. These can include:

Poor pricing.

Weak record keeping.

Limited market research.

Poor customer service.

Inadequate marketing.

Cash flow problems.

Failure to understand the numbers.

Giving these businesses more money often delays the problem rather than solves it. Imagine pouring water into a bucket with several holes. Adding more water does not stop the leaks. The leaks must be repaired first. Businesses operate much the same way.

Borrowing Before You’re Ready

One situation we encounter regularly is the entrepreneur who wants to borrow to purchase expensive equipment, rent a large office or invest heavily in inventory before making their first sale. Now there is certainly nothing wrong with ambition. The danger lies in assuming that investment automatically creates demand. Customers do not buy because you’ve purchased expensive equipment. They buy because you solve a problem, they are willing to pay for. Many successful businesses began with modest resources. They reinvested profits gradually rather than borrowing heavily from the outset. That approach reduced financial pressure and allowed the business to grow at a sustainable pace.

But Is Borrowing Always Wrong?

Not at all. This is where context matters. There are many legitimate reasons for businesses to borrow. A manufacturing company may need specialised machinery. A transport business may require commercial vehicles. An established retailer may borrow to expand into a second location. A growing business may need additional working capital to fulfil larger contracts. These are very different situations from borrowing to test whether a business idea might work. The difference is that an established business has evidence: it has customers, it has sales history, it has financial records, it understands its market. In these circumstances, financing often becomes a tool for growth rather than survival.

Borrow to Grow, Not to Guess

Perhaps the most useful lesson entrepreneurs can take from Cuban’s comments is this:

Borrow to grow a proven business, not to guess whether an unproven idea will succeed.

Before approaching a lender, ask yourself:

  • Have I already tested this business idea?
  • Do I understand exactly who my customers are?
  • Have I priced my products or services correctly?
  • Can I realistically meet loan repayments if sales are slower than expected?
  • Have I explored lower-cost ways of starting first?

These questions are often more valuable than the loan itself.

A Better Starting Point

Many businesses today can begin much smaller than entrepreneurs realise. Consultants can start with virtual advisory sessions. Tutors can teach online before renting classrooms. Retailers can validate demand through social media before investing in large quantities of stock. Service providers can begin from home before leasing commercial premises.

Testing an idea on a smaller scale allows entrepreneurs to learn what customers actually want before making significant financial commitments.

The Timely Takeaway

Mark Cuban’s statement may sound harsh, but it highlights an important truth.

Money should support a good business. It cannot create one.

Before borrowing, entrepreneurs should ensure they understand their market, know their numbers and have evidence that customers are willing to buy. Debt is neither good nor bad. It is simply a financial tool, which, if used wisely, can accelerate growth. Used too early, it can magnify risk. The goal should never be to borrow as much as possible, but it should be to build a business strong enough that financing becomes an opportunity rather than a necessity.

How We Help

At The Timely Entrepreneur Resource and Research Centre, many entrepreneurs approach us asking where they can find funding.

Our first response is often another question:

“Is your business truly ready for funding?”

Through our Business in Trouble (BIT) Sessions and business advisory services, we work with entrepreneurs to assess business readiness before they assume additional financial obligations. Together, we review business models, pricing, cash flow, profitability, financial projections and operational readiness, helping business owners make informed decisions rather than expensive mistakes.

Sometimes the best financial decision is not borrowing more. Sometimes it is building a stronger business first.

Helping businesses start, survive and grow.

🌐 new.thetimelyentrepreneur.com

📧 thetimelyentrepreneur2@gmail.com

📞 (868) 488-0507 | (868) 706-5934


Business Diagnosis: A recurring editorial series from The Timely Entrepreneur Resource and Research Centre examining the issues affecting entrepreneurs and MSMEs in Trinidad and Tobago, together with practical ways businesses can respond.

When Customers Stop Spending: Understanding Today’s Business Slowdown

Helping entrepreneurs understand what’s really happening inside the economy and inside their businesses.

Over the past few weeks, we’ve had conversations with entrepreneurs from different industries, and we’ve been following the business news closely. One comment keeps coming up: – “Business has slowed.” Retailers are saying fewer customers are walking through their doors; service providers are receiving enquiries, but fewer people are committing. Some businesses are seeing customers delay purchases, while others are noticing that clients are buying less than they did just a few months ago. The question is, why?

The current business environment presents several challenges for entrepreneurs.

Business organisations have continued to express concerns about higher operating costs, foreign exchange constraints, increased business expenses and softer economic activity. These issues have placed pressure on many businesses across Trinidad and Tobago. At the same time, we are entering one of the most predictable spending periods of the year.

For many households, July and August are no longer ordinary months. They are back-to-school months. Parents are purchasing uniforms, textbooks, school shoes, stationery, transportation, electronic devices and paying registration fees for the new school term beginning in September.

When household budgets are stretched, spending priorities naturally change. This does not necessarily mean consumers have stopped spending; it often means they are spending differently. They have simply changed what they are spending on. Understanding that distinction is important. Economists often describe this as a shift from discretionary spending to essential spending. 

For businesses, this can feel like a sudden slowdown. But in reality, customer priorities have simply shifted. Recognising this shift is important because it helps business owners respond strategically rather than emotionally. For many households, these expenses become the priority.

Money that might previously have been spent on dining out, beauty services, entertainment, clothing or discretionary purchases is now redirected (for the next two months at least) towards education.

Consumer Behaviour Has Changed

Instead of asking,“Do I want this?”, they begin asking, “Do I need this right now?”, “Can this wait another month?”, “Is there a less expensive alternative?”, “Will this purchase solve an immediate problem?”

They are signs that customers are thinking differently and businesses that recognise this shift early are usually better positioned to respond.

Business Diagnosis

A temporary slowdown in sales is not necessarily a sign that your business is failing. It may be telling you something else. Perhaps your customers now need more flexible payment options. Perhaps your products or services need to be presented differently. Perhaps this is the right time to strengthen relationships with existing customers rather than focusing only on attracting new ones. Perhaps your pricing, marketing or customer experience needs to be reviewed. Every slowdown provides information. The challenge is learning how to interpret it.

Responding to Changing Consumer Priorities

Economic slowdowns rarely affect every business in exactly the same way. Some businesses continue growing. Others experience significant declines. The difference often lies in how quickly they recognise changing customer behaviour. Businesses should ask themselves an important question:

Has the way my customers buy changed?

If the answer is yes, the business may need to adapt. This does not interpret into lowering prices, as many businesses rush to do when sales aren’t moving. In fact, constant discounting can often make profitability even worse. Instead, entrepreneurs should consider whether their products or services can be presented differently. Could smaller service packages make purchasing easier? Would payment plans encourage customers to proceed? Could products be bundled to increase value? Would subscription or membership options improve recurring income? Can premium services be complemented by more affordable entry-level options?

The objective is not simply to sell more. It is to remain relevant to changing customer needs.

Sometimes the Business Model Needs to Change

One of the greatest dangers during slower periods is assuming that doing more of the same will produce different results. Markets evolve, and so too, do customer expectations, and hence, businesses must evolve too.

A tutor who previously offered only private lessons may introduce small group classes. A restaurant may create family meal packages or corporate lunch specials. A consultant may offer shorter advisory sessions for clients unable to commit to larger projects. A retailer may strengthen online sales and delivery services. A beauty salon may introduce express treatments for customers seeking more affordable options. A contractor may expand into maintenance contracts that generate recurring income rather than depending entirely on new construction projects.

One area of business we see struggling consistently is Consultancy. Consultancies are among the first businesses to feel an economic slowdown because many clients view consulting as something they can postpone. However, the businesses that survive don’t stop selling expertise. They repackage it to match what clients can afford and need at that moment.

Perhaps think in terms of a value ladder, where clients can enter at different price points instead of assuming everyone is ready for a full consulting engagement. Rather than assuming every client is ready for a comprehensive consultancy engagement, consider developing a range of services at different investment levels. A business that cannot commit to a full consulting package today may still invest in a one-hour Business Health Check, a Pricing Review, a Compliance Assessment or a Business Recovery Session. Smaller engagements often build trust, solve immediate problems and naturally lead to larger consulting opportunities when the client’s circumstances improve. These adjustments do not change the identity of the business. They simply reflect a willingness to respond to current market conditions. History consistently shows that businesses prepared to adapt are often the ones that emerge strongest after periods of economic uncertainty.

Slow Periods Can Become Growth Periods

Many entrepreneurs view slower periods as lost time. In reality, they can become some of the most valuable months in the business calendar. When customer demand slows, owners finally have time to work on the business instead of constantly working in it.

This is an ideal opportunity to:

  • Review pricing.
  • Analyse profitability.
  • Identify hidden profit leaks.
  • Improve record keeping.
  • Strengthen customer relationships.
  • Reconnect with past clients.
  • Update marketing materials.
  • Improve social media presence.
  • Review supplier costs.
  • Improve inventory management.
  • Formalise business processes.

Businesses that invest in improvement during quieter periods often recover faster when demand increases.

Questions Worth Asking

If business has slowed, ask yourself:

  • Have my customers’ spending priorities changed?
  • Am I communicating the value of my products or services clearly?
  • Have I stayed in contact with existing customers?
  • Have I reviewed my expenses over the past three months?
  • Are there complementary products or services I could introduce?
  • Is my cash flow strong enough to manage seasonal fluctuations?
  • Am I relying too heavily on one source of income?
  • Could my business benefit from introducing something new?

These questions won’t solve every challenge, but they often reveal opportunities that are easy to overlook when you’re busy running the business.

The Timely Takeaway

Economic slowdowns test every business. Some businesses respond by waiting. Others respond by adapting. Entrepreneurs cannot control inflation. They cannot control consumer confidence. They cannot control foreign exchange availability. They cannot control household spending.

They can, however, control how prepared their businesses are to respond. The businesses most likely to succeed are not always the largest. They are often the ones that understand their customers, know their numbers, manage their costs and remain willing to adapt when circumstances change.

Sometimes the greatest opportunity for growth begins during a period that initially feels like decline.

How We Help

At The Timely Entrepreneur Resource and Research Centre, our Business in Trouble (BIT) Sessions help entrepreneurs look beyond the symptoms.

A slowdown in sales is often only one part of the story. Together, we examine pricing, cash flow, expenses, profitability, customer trends, business systems and operational practices to identify what is really affecting performance. Sometimes the issue is the economy; other times it is the business. More often, it is a combination of both.

Helping businesses start, survive and grow.

🌐 new.thetimelyentrepreneur.com

📞 (868) 488-0507 | (868) 706-5934

Timely Business Action Plan

This Week’s Actions

☐ Review your July and August sales against last year.

☐ Contact five existing customers.

☐ Review your three highest-cost expenses.

☐ Identify one service you could repackage.

☐ Schedule one hour to work on your business instead of in it.

☐ Review your pricing.

To protect client confidentiality, identifying details have been changed. The situations described are based on real business challenges encountered through our work with entrepreneurs.

Real business situations. Practical lessons for entrepreneurs.

Recently, during one of our Business in Trouble (BIT) Sessions, we reviewed a service-based business that, from the outside, appeared to be doing well: appointments were fully booked most weeks, customers kept returning, the business had built a loyal client base, and anyone looking at the appointment book would probably conclude that business was thriving.

Yet, during our discussion, the owner made a remark that suddenly had them thinking…

“If business is so busy, how come we don’t see this reflected in dollars and cents at the end of the month?”

Digging further, here’s what we found: it wasn’t a lack of customers, it wasn’t poor service and it wasn’t about the marketing. We discovered the hidden profit leaks.

Like many entrepreneurs, the owner had become so focused on serving customers that several small issues had quietly developed over time. Individually, they didn’t seem important. Together, they were steadily reducing the business’s profitability.

Hidden Profit Leak No. 1

Prices Hadn’t Kept Pace with Rising Costs

The salon’s prices had remained largely unchanged for several years. Meanwhile, the cost of products, utilities, rent and everyday operating expenses had continued to increase. Every appointment still generated income, but each one was contributing less profit than before.

Many business owners believe staying competitive means keeping prices low. Unfortunately, failing to review pricing regularly often means the business quietly absorbs rising costs instead.

Hidden Profit Leak No. 2

Time Was Being Given Away

Appointments were scheduled for one hour. But many lasted much longer. Clients frequently requested an additional service or “just one more thing.” Because the owner genuinely cared about customer satisfaction, she rarely charged for the additional time. Over weeks and months, those extra fifteen or twenty billable minutes became several hours of unpaid work.

For a service-based business, time is inventory. Once it has been given away, it can never be sold again.

Hidden Profit Leak No. 3

Small Purchases Were Becoming Big Expenses

Whenever supplies ran low, another trip to the beauty supplier seemed necessary. Whether it be a bottle of shampoo, disposable gloves, styling products, coffee, or even a small chicken roti while out. Each purchase seemed insignificant. But they represented hundreds of dollars every month that had never been budgeted.

Hidden profit leaks often begin with spending that nobody thinks is worth tracking.

Hidden Profit Leak No. 4

Missed Appointments Were Going Unpaid

Some clients cancelled at the last minute; others simply didn’t show up. Because there was no cancellation policy, those appointment times remained empty. Unlike a retailer that can sell the same product tomorrow, a salon loses that income forever once the appointment time has passed. One missed appointment may not seem serious. Several missed appointments every month can significantly affect profitability.

Hidden Profit Leak No. 5

Personal and Business Money Were Mixed Together

Throughout the week, business income was regularly used to purchase groceries, gas and other household expenses. By the end of the month, it became difficult to determine how much profit the business had actually earned. Without reliable financial information, business decisions become based on assumptions rather than facts.

Understanding where your money is going is just as important as understanding where it is coming from.

What We Found

This business simply needed to stop the money that was quietly leaking out of the business.

After reviewing pricing, introducing a cancellation policy, improving inventory management and separating business and personal finances, the salon became more profitable without attracting a single new client.

The number of customers remained almost exactly the same. The difference was that more of the money being earned stayed in the business.

Questions Worth Asking

Before assuming your business needs more customers, take a moment to ask yourself:

  • Are my prices still appropriate for today’s costs?
  • Am I giving away products, services or time without charging for them?
  • Do I know exactly where my money is going every month?
  • Could small, everyday habits be quietly reducing my profits?

Sometimes the quickest way to improve profitability isn’t by increasing sales. Sometimes it’s by identifying the money that’s already slipping through the cracks.

If those questions made you stop and think, your business may benefit from a closer review.

The Timely Takeaway

A busy business is not always a profitable business. Before investing more money in advertising or trying to attract more customers, first determine whether hidden profit leaks are reducing the income you’re already earning.

How We Help

Through our Business in Trouble (BIT) Sessions, The Timely Entrepreneur Resource and Research Centre works alongside entrepreneurs and MSMEs to examine what is really happening inside their businesses. We don’t simply look at sales. We examine pricing, cash flow, expenses, profitability, business systems, compliance and the day-to-day decisions that influence long-term performance.

Sometimes a fresh set of experienced eyes can identify opportunities and problems that are easy to miss when you are busy running the business. Every business has a story. Sometimes the numbers tell a different one. If your business feels busy but the results aren’t matching the effort, it may be time to look beneath the surface.

Helping businesses start, survive and grow.

🌐 new.thetimelyentrepreneur.com 📞 (868) 488-0507 | (868) 706-5934


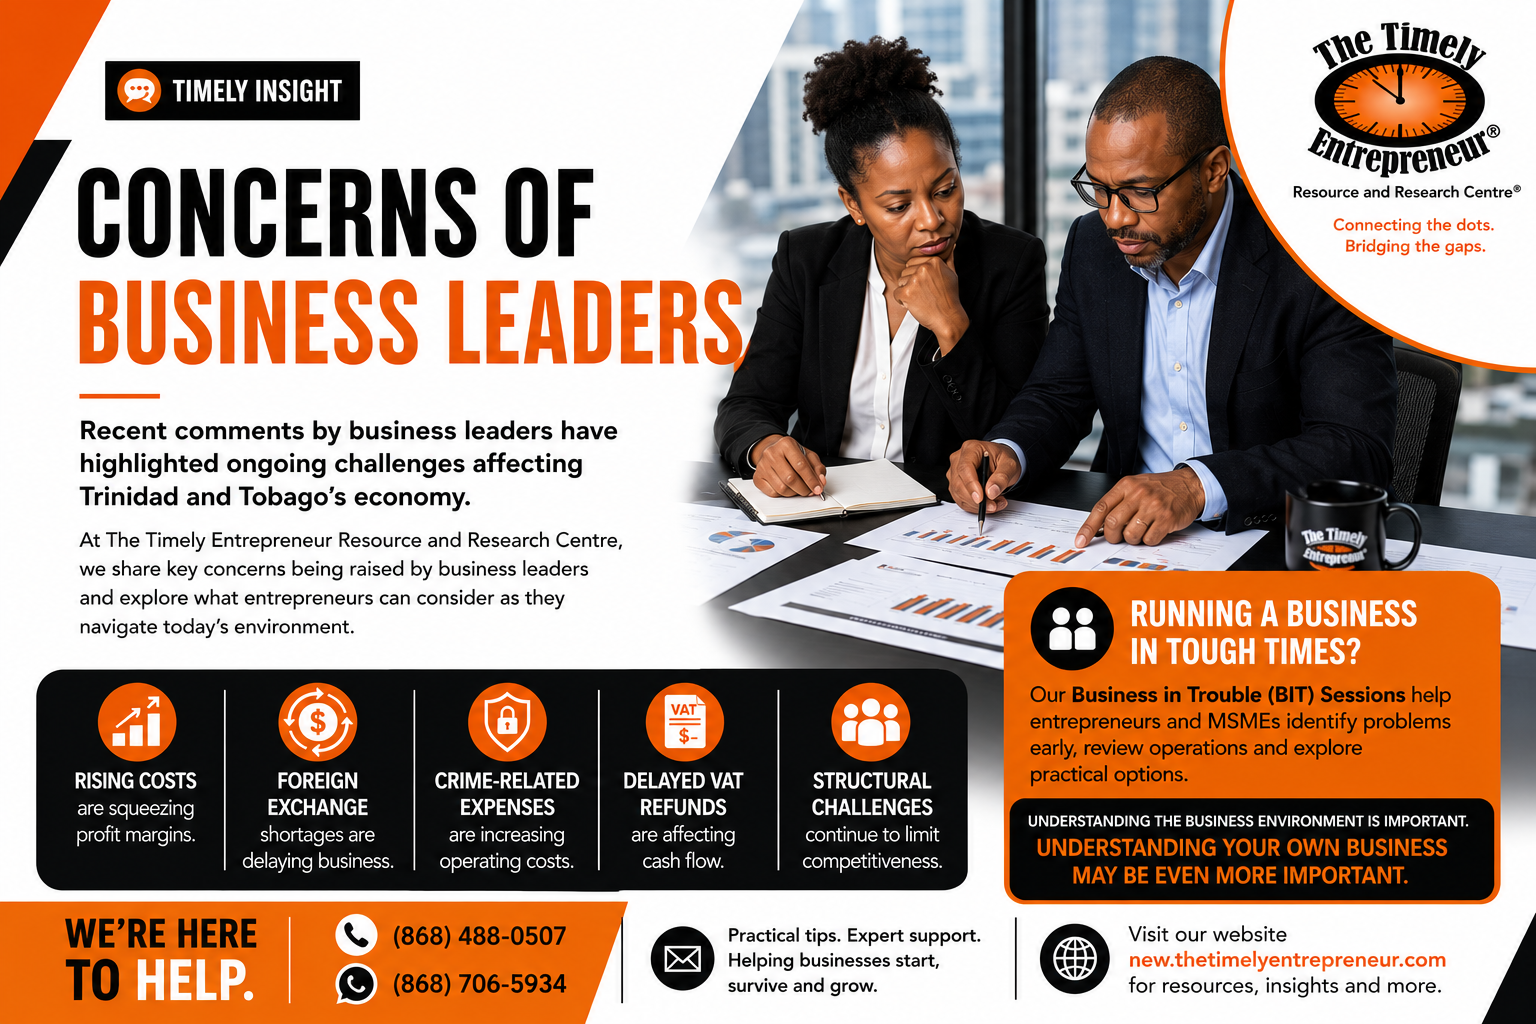
Recent comments by businessman Robin Ojeer and Sieunarine Kumar Hardath, director of Hardath General Insurance Consultants Ltd, have reignited discussion about the state of Trinidad and Tobago’s economy. Both businessmen point to issues that many entrepreneurs and business owners have been quietly confronting for years: rising operating costs, foreign exchange constraints, delayed VAT refunds, crime-related expenses and what they perceive as a lack of meaningful progress on deeper structural challenges affecting the economy.

Read the full article via Guardian Media here: https://www.guardian.co.tt/business/tts-economy-is-dying-businesses-lash-govt-policies-6.2.2608899.34357468a3#google_vignette

At The Timely Entrepreneur Resource and Research Centre, we believe these concerns deserve careful consideration, not because they represent isolated opinions, but because they reflect realities being experienced across the business landscape. Whether one agrees with every criticism or not, the observations made by Ojeer and Hardath raise important questions about confidence, competitiveness and the operating environment facing micro, small and medium-sized enterprises. More importantly, they remind us that understanding the broader economy is essential for entrepreneurs seeking to make sound decisions in increasingly uncertain times.

These rising operating costs, crime-related expenses, limited access to foreign exchange and increasing uncertainty are creating conditions that are becoming difficult for many firms to navigate. Recent reactions to the Mid-Year Budget Review have highlighted concerns that the challenges facing businesses are not being adequately addressed.

For many entrepreneurs, these concerns are not theoretical. They are being experienced every day.

Security costs continue to rise. Businesses are spending more on cameras, alarms, gates, insurance and private security, adding another layer of expense to already strained operations. Small businesses, which often operate on tight margins, are finding it increasingly difficult to absorb these additional costs.

The foreign exchange shortage remains another major source of concern. Importers and manufacturers are experiencing delays and uncertainty when trying to access US currency to purchase goods and raw materials. Businesses that depend on imported products are often forced to source foreign currency elsewhere at higher costs, which eventually affects pricing and profitability.

Economic uncertainty itself creates another problem. When consumers become cautious about spending, businesses experience slower sales and reduced cash flow. Expansion plans are delayed, investments are postponed and confidence weakens.

While many business owners are looking to government policies for relief, entrepreneurs must also recognise that survival cannot depend entirely on external solutions. Businesses that are waiting for perfect economic conditions may find themselves waiting indefinitely.

This period calls for stronger internal management and greater adaptability.

Business owners should pay close attention to cash flow and reduce unnecessary expenses. Inventory management, debt collection and pricing decisions require constant review. Businesses that understand their numbers are generally better positioned to respond to changing conditions.

Diversification is becoming increasingly important. Companies that rely heavily on a single customer, product or revenue stream face greater vulnerability. Exploring new markets, introducing complementary services and embracing digital opportunities can help reduce risk.

Local sourcing should also be considered where possible. Although not every imported item can be replaced, businesses that develop relationships with local suppliers may reduce some of their exposure to foreign exchange challenges.

Another area requiring attention is business formalisation and compliance. In difficult economic times, access to financing, partnerships and growth opportunities often favours businesses that maintain proper records and operate within regulatory requirements. Informal businesses may find themselves excluded from opportunities precisely when they need them most.

This reality is particularly relevant in our business eco-system, where many micro and small enterprises operate successfully for years without formal registration, proper records or full compliance. Home-based caterers, online retailers, hairdressers, barbers, tutors, contractors, event planners and service providers often generate steady income and maintain loyal customers, yet remain vulnerable when circumstances change. During difficult economic periods, these businesses may discover that the absence of proper systems and documentation limits their ability to access loans, secure insurance, participate in government procurement, attract investors or form partnerships with larger organisations.

Ironically, the very moment when a business needs support, whether because of rising costs, declining sales or the need to expand into new markets, is often when informality becomes a disadvantage. A contractor with years of experience but no documented financial records may struggle to obtain financing. A home-based food business may be unable to supply larger institutions. An online retailer with strong sales may find itself excluded from opportunities requiring proof of income, business registration or compliance. In an increasingly demanding environment, formalisation is no longer simply about satisfying regulatory requirements. It is about positioning businesses to access opportunities, withstand shocks and remain competitive.

Perhaps the greatest danger facing businesses today is not simply the economic environment, but the temptation to become paralysed by uncertainty, as we have been seeing here at The Timely Entrepreneur. Difficult periods demand careful decisions, but they also require action.

Trinidad and Tobago has faced economic challenges before. Businesses have survived recessions, pandemics, foreign exchange shortages and changing markets. Those that endured were not necessarily the largest or the strongest. They were often the ones willing to adjust, rethink and remain disciplined.

The concerns being raised by businesses deserve serious attention. Because while entrepreneurs cannot determine national economic policy, they can determine how prepared their businesses are to navigate an increasingly demanding environment. However, entrepreneurs cannot afford to surrender their future to circumstances beyond their control. Economic conditions may be challenging, but good management, sound decision-making and adaptability remain powerful tools for survival.

At The Timely Entrepreneur Resource and Research Centre, we continue to believe that knowledge, preparation and practical support remain essential for businesses seeking not only to survive difficult times, but to position themselves for long-term growth.

While uncertainty may be unavoidable, helplessness is not!

Is Your Business Feeling the Pressure?

If rising costs, declining sales, cash flow challenges or uncertainty about the next step are beginning to affect your business, it may be time for an objective review.

Through our Business in Trouble (BIT) Sessions, The Timely Entrepreneur Resource and Research Centre works with entrepreneurs and MSMEs to identify problems early, review operations and explore practical options before small issues become major crises.

Understanding the business environment is important. Understanding your own business may be even more important.


The 2026 economic reality

The team at The Timely Entrepreneur Resource and Research Centre met recently to discuss the Economic Outlook for 2026. Here is a direct, unsentimental assessment for 2026, written for people who actually have to survive in the Trinidad and Tobago economy.

Stripped of comfort language

The outlook for 2026 is fragile and deteriorating beneath the surface. The headline numbers still lean on energy, but the underlying economy is showing classic late-cycle stress. Growth is narrow, costs are sticky, foreign exchange remains structurally constrained, and the State’s room to cushion shocks is shrinking.

Energy revenues may hold up on paper, but gas supply constraints, maintenance downtime, and global price volatility mean cash flows will be uneven. Non-energy growth is weak because domestic demand is under pressure and operating costs are rising faster than incomes. See more below:-

Why non-energy growth in Trinidad and Tobago is weak

1. Real household income is falling

Wages in the non-energy economy have not kept pace with cumulative increases in food, utilities, rent, transport, insurance, and education costs. When real income declines, discretionary spending contracts. Non-energy sectors depend heavily on domestic consumption, so lower purchasing power translates directly into weaker sales volumes.

2. Domestic demand is narrow and concentrated

Consumption is concentrated in essentials. Spending on non-essential goods and services is being postponed or reduced. This limits growth in retail, hospitality, personal services, creative industries, and discretionary manufacturing.

3. High operating costs compress margins

Non-energy businesses face rising electricity charges, logistics costs, rent, security, insurance, and compliance expenses. These costs increase faster than revenues, forcing firms to scale back operations, delay expansion, or exit markets.

4. Foreign exchange constraints restrict supply

Non-energy sectors are import-dependent for inputs, equipment, raw materials, and inventory. FX shortages delay restocking, raise supplier prices, and reduce production capacity. Firms cannot scale output without reliable access to foreign exchange.

5. Limited access to affordable credit

Tighter bank lending standards, higher interest rates, and stricter documentation requirements reduce financing for expansion, working capital, and technology upgrades in non-energy sectors.

6. Weak productivity growth

Capital investment outside energy is limited. Many firms operate with outdated equipment, inefficient processes, and limited automation. Productivity gains are insufficient to offset rising costs, keeping unit costs high.

7. Public sector consolidation dampens spillovers

Fiscal restraint limits public-sector driven demand and procurement spillovers that historically supported non-energy activity. Delays in State payments further constrain cash flow for contractors and suppliers.

8. Small market size limits scale

Trinidad and Tobago’s domestic market is limited. Without consistent export expansion, non-energy firms face saturation quickly, capping growth potential.

9. Business confidence is fragile

Uncertainty around taxes, compliance enforcement, energy prices, and economic policy timing reduces private investment. Firms postpone hiring, capital spending, and market expansion.

10. Structural dependence on energy revenues

Non-energy activity remains indirectly tied to energy through public spending, FX availability, and liquidity. When energy performance softens or becomes volatile, non-energy sectors slow even if their fundamentals are unchanged.

These factors operate simultaneously. The result is low volume growth, thin margins, and limited expansion capacity across the non-energy economy.

Inflation is no longer the sudden spike of previous years. It is now embedded. Food, utilities, insurance, logistics, rent, compliance costs, and financing charges are resetting at higher levels and staying there. That is more dangerous for small businesses than short bursts of inflation, because it erodes margins quietly and continuously.

The foreign exchange situation remains a structural problem. It is not a temporary shortage. Import-dependent businesses will face delays, higher supplier demands for prepayment, and periodic inability to restock. This will worsen as global credit tightens and correspondent banking becomes more conservative.

Government Policy Impacts

Government policy in 2026 signals restraint, not rescue. Here is what this really means in concrete, observable terms.

1. No broad stimulus spending

The 2026 fiscal stance is not expansionary. There is no large-scale injection of new spending designed to boost demand across the economy. Capital expenditure is selective and controlled, not wide-ranging. This means the State is not stepping in to lift consumption or offset private-sector weakness.

2. Tight control over recurrent expenditure

Government is focused on containing wage growth, transfers, and subsidies. Any increases are targeted and limited. This signals that protecting fiscal balances is a higher priority than cushioning households or businesses broadly.

3. Rationalisation of subsidies and concessions

Energy, utility, and social subsidies are being reviewed and narrowed. The direction is toward reducing fiscal leakage, not expanding relief. Businesses should expect less price buffering from the State and more exposure to real market costs.

4. Emphasis on compliance and revenue collection

Policy focus has shifted from accommodation to enforcement. Tax compliance, NIS contributions, fees, and penalties are being tightened. This raises revenue without stimulating activity and increases operating pressure on firms that are marginal or informal.

5. Cost-shifting rather than cost-absorption

Instead of absorbing rising costs, government policy increasingly passes them through to users and businesses. Examples include higher fees, utility adjustments, and reduced concessions. This is a restraint signal because it prioritises fiscal sustainability over short-term relief.

6. Limited intervention in distressed sectors

There is no clear framework for widespread bailouts, debt relief, or emergency support for struggling industries or MSMEs. Assistance is conditional, case-by-case, or indirect. Firms cannot assume the State will step in if conditions worsen.

7. Conservative fiscal assumptions

Budget projections rely on cautious spending paths rather than optimistic growth-driven revenue expansion. This reflects risk aversion and a desire to preserve buffers, not deploy them aggressively.

8. Protection of fiscal buffers over economic stimulus

Foreign reserves, the Heritage and Stabilisation Fund, and debt metrics are being preserved. The State is signalling that these buffers are for systemic crises, not for sustaining weak growth or propping up businesses.

What this means in plain terms

The Government’s posture in 2026 is one of containment and discipline, not economic rescue. It is managing downside risk to public finances rather than attempting to reignite growth through spending or relief.

For businesses and households, this means:

  • Do not expect sweeping relief measures.
  • Do not rely on subsidies to stabilise costs.
  • Do not assume government intervention if cash flow tightens.

The burden of adjustment is being shifted to the private sector and households. 

Subsidies are being rationalised, compliance is tightening, and social spending is being re-targeted. Small businesses should assume less tolerance for arrears, less flexibility from State agencies, and more scrutiny, not more support. Click the link to read more on this here: Build Wealth, Don’t Depend on NIS

Hard truths small businesses must accept now

First, revenue instability is the new normal. If your business requires steady monthly sales just to survive, it is already at risk.

Second, cost increases will not reverse. Electricity, rent, shipping, and insurance costs in Trinidad and Tobago are structurally higher, not temporarily elevated. They are driven by fuel pricing, utility cost recovery, insurance risk re-pricing, global logistics costs, crime exposure, and tighter regulatory requirements. None of these drivers are reversing in the near term.

Businesses that delay price adjustments, cost restructuring, or operating changes in the hope that these expenses will fall are basing decisions on expectation rather than evidence. Since revenues are not rising at the same pace, waiting erodes margins, drains cash, and weakens the business each month.

In practical terms, hoping costs will fall postpones necessary action and increases the risk of failure.

Third, access to finance will tighten further. Banks will lend, but only to businesses that can show discipline, documentation, and predictable cash flows. Informality will be punished quietly simply through denial. In 2026, informal businesses are unlikely to be shut down publicly or aggressively. Instead, they will be excluded. They will be denied access to bank financing, government contracts, corporate clients, digital payment platforms, insurance coverage, and formal partnerships because they cannot meet documentation, compliance, or reporting requirements. No warning is required for this to happen.

The punishment is quiet because the business is not confronted or prosecuted. It simply finds that doors stop opening, opportunities disappear, and growth becomes impossible.

Fourth, customer behaviour has changed permanently. Households are trading down, delaying purchases, sharing services, and questioning value more aggressively. Loyalty is thinner. Price sensitivity is higher. Households and businesses have less discretionary income and tighter cash flow. Customers compare prices more closely, trade down to cheaper alternatives, reduce quantities, or stop buying altogether when prices rise. This means small price increases now trigger stronger reactions than in the past, directly affecting sales volume and customer retention.

Fifth, compliance is no longer optional camouflage. Businesses that “fly under the radar” will struggle to scale, access credit, or partner with corporates and institutions.

What small businesses must do immediately to survive 2026

1. Ruthless financial control

You must know, weekly, not monthly:

  • Which products or services actually generate cash.
  • Which ones only generate activity.
  • Your true break-even point with current costs, not last year’s.

Cut offerings that drain cash, even if they are popular or emotionally attached. Popular does not pay bills.

Move from annual thinking to rolling 90-day cash forecasting. If you cannot see three months ahead, you are already late.

2. Rebuild pricing around reality, not fear

Many small businesses are underpricing out of fear of losing customers. In 2026, underpricing is more dangerous than losing low-value customers.

You must:

  • Separate price-sensitive customers from value-driven ones.
  • Create tiered offerings, not one price for everyone.
  • Be explicit about what costs more and why.

If customers cannot accept price increases, then reduce scope, not margins.

3. Reduce dependency risks

If your business relies on:

  • One supplier.
  • One major customer.
  • One income stream.
  • One location.
  • One platform.

You are exposed.

Diversify suppliers locally where possible, even at slightly higher unit cost. Reliability beats cheap in unstable conditions.

Build at least one secondary income line that is not dependent on imports or long credit chains.

4. Formalise selectively but properly

You do not need excessive bureaucracy, but you do need:

  • Clean records.
  • Up-to-date filings.
  • Basic management accounts.

This is not about pleasing the State. It is about surviving when cash tightens and only disciplined businesses can negotiate, borrow, or pivot.

5. Shift from growth obsession to resilience

2026 is not about rapid expansion. It is about endurance.

That means:

  • Smaller, stronger operations.
  • Fewer fixed costs.
  • More variable cost models.
  • Leasing instead of buying where possible.
  • Partnerships instead of solo scaling.

Practical income generation and diversification paths that make sense now

Not all diversification is smart. Many small businesses fail because they chase everything. The following directions reflect actual economic pressure points:

1. Service over product where possible

Services:

  • Require less foreign exchange.
  • Adjust prices faster.
  • Carry lower inventory risk.

Knowledge-based services, maintenance, training, compliance support, repair, and local logistics will outperform imported retail over the next two years.

2. Recurring income models

One-off sales are unstable in a tightening economy.

Think in terms of:

  • Retainers.
  • Subscriptions.
  • Maintenance contracts.
  • Memberships.
  • Bundled service periods.

Predictability is power in uncertain conditions.

3. B2B over B2C where feasible

Households are under pressure. Businesses still need services to operate.

Target:

  • SMEs that must remain compliant.
  • Corporates outsourcing non-core functions.
  • Schools, NGOs, and institutions with budgeted spending cycles.

Margins may be tighter, but payments are more predictable.

4. Local substitution niches

Import friction creates opportunity.

Look for:

  • Products or services businesses importing simply because “that’s how it’s always been.” Many businesses continue importing certain products or services out of habit rather than necessity. The original reasons may have been quality, availability, or cost advantages that no longer exist. In the current environment, import dependence driven by routine rather than analysis increases exposure to foreign exchange shortages, shipping delays, and higher costs, even when local or regional alternatives could meet the need adequately.
  • Small-batch local alternatives – this refers to locally produced goods or services made in limited quantities that substitute for imported products. They reduce foreign exchange exposure, shorten supply chains, and allow faster price and product adjustments. They may not match large-scale imports on volume or unit cost, but they offer reliability, flexibility, and resilience in a constrained economic environment.
  • Hybrid models where part of the value is local. Hybrid models are business arrangements where some components are imported, but a significant portion of the value creation happens locally. This can include local assembly, customization, servicing, packaging, or distribution. These models reduce foreign exchange exposure, lower logistics risk, and allow businesses to maintain functionality and quality while adapting to supply constraints and cost pressures.

You do not need to replace imports entirely. You only need to reduce dependency.

5. Regional and digital income streams

TT is a small market with limited growth.

Digital services, remote consulting, content-based products, online training, and regional service delivery reduce dependence on local demand alone. Foreign currency income is a buffer, not a luxury.

The uncomfortable conclusion

2026 will not reward hope, optimism, or hustle alone. It will reward discipline, realism, and adaptability.

Small businesses that survive will not be the loudest or most visible. They will be the ones that:

  • Control cash tightly.
  • Price honestly.
  • Cut early rather than late.
  • Diversify carefully, not emotionally.
  • Accept that the environment has changed and act accordingly.

This is not an economic collapse where all businesses fail at once. Economic activity continues, but under tighter conditions. It is a sorting phase where businesses with weak finances, poor pricing, high dependency, or low discipline are pushed out, while those that are well-managed, adaptable, and resilient remain and gain market share.

Businesses that adjust now will still be standing when conditions improve. Those that wait for things to “go back to normal” will quietly exit.

“Our population is ageing, and it is doing so rapidly. In 1980, only about five per cent of our citizens were aged 65 or older. Today, that number stands at over 11 per cent. By the year 2060, it is expected to more than double to 26 per cent. Think carefully about what that means.”

“This is a reality that this government refuses to ignore. The national insurance system is already under serious strain. ” – Davendranath Tancoo, Minister of Finance, Trinidad and Tobago


“DO NOT RELY SOLELY ON NIS FOR FUTURE WEALTH”

Here’s a reflective and practical look at the recent advice from Davendranath Tancoo, Minister of Finance, Trinidad and Tobago, when he urged citizens not to rely solely on the National Insurance Board of Trinidad and Tobago (NIS) for future wealth. The reference used throughout  for this article is https://newsday.co.tt/2025/10/25/tancoo-build-wealth-dont-depend-on-nis/#:~:text=FINANCE%20minister%20Dave%20Tancoo%20has%20warned%20that%20TT%E2%80%99s,%28NIS%29%20and%20new%20initiatives%20to%20mobilise%20domestic%20capital. (unless otherwise stated/shown)

We’ll highlight why his advice makes sense, examine the economic and socio‐political context, and offer realistic steps individuals can follow to build their own financial resilience.

Why his message matters

Minister Tancoo made it clear that the days of depending “solely on the National Insurance System, on government assistance, are coming to an end.” He pointed out that the government intends to deepen capital markets and offer instruments that allow citizens to invest in productive assets.

From a broader perspective, this assurance stems from the fact that:


  • As a result, expecting the NIS to deliver full retirement security or substantial wealth accumulation without individual action is risky.

The current context in Trinidad and Tobago

To put the minister’s advice into context, here are key facts:

  • The economy: “Fraught with uncertainty and underwhelming, albeit steady performance, the global economy in 2025 will see its slowest growth since the COVID-19 pandemic, stemming primarily from a series of shocks from the United States (US) trade policy and other volatile geo-political tensions around the world. As such, the IMF has forecasted global growth to falter to 3.0 percent in 2025. Similarly, the World Bank (WB), expects growth to weaken to 2.3 percent in 2025, with decelerations in most economies as compared to 2024. Despite the weakened outlook, the global economy is not expected to fall into a recession.” Review of the Economy 2025 – finance.gov.tt.
  • The NIS fund: It is one of the pillars of social protection, but actuarial reviews and recent data show a diminishing ratio of contributors to beneficiaries and real pressures on investment returns.
  • Socio‐political factors: With pressures from inflation, global uncertainty, and structural constraints (such as dependence on one or two sectors), individuals cannot assume the status quo will persist. The government’s budget shows recognition of “deep structural imbalances” and emphasis on restoring fiscal stability.

In short: you are operating in an environment where the state-provided safety net (via NIS) is still crucial but cannot reasonably be the only foundation for wealth creation.

Realistic approaches for individuals

Here are practical steps you and other citizens can adopt, given the context:

Start by clarifying your goals.

Ask: What does “wealth” mean for me? When do I want financial independence or retirement to happen? How much income will I need then? Setting concrete targets helps you determine how much you must save and invest.

Build a savings and investment habit now.

Waiting until later reduces your flexibility. There are articles showing that in Trinidad and Tobago, saving more than the typical 10 % of income can make a big difference in wealth accumulation.
Given the environment, aim for a savings rate you can sustain, and channel that into assets beyond just deposit accounts, because inflation erodes cash value.

Diversify away from depending solely on NIS or one asset class.

Since NIS cannot guarantee generous outcomes alone, it makes sense to build multiple income/asset streams: e.g., equities, property, mutual funds, small business ventures, and so on. Minister Tancoo’s focus on enabling citizens to invest in public bonds and Real Estate Investment Trust (REITs) suggests the government sees capital market participation as a vector.

 
Real estate trust to unlock ‘national wealth’ to ordinary citizens


By spreading risk, you reduce exposure to any single failure point.

Use available local instruments wisely, while keeping an eye on global possibilities.

The government is launching new vehicles (such as a state real-estate vehicle and a national investment fund bond) that aim to broaden participation. – see above reference article.
That said, always analyse fees, risk levels, and liquidity. Don’t automatically assume “government-backed” means zero risk. Also consider investing in global exposure where feasible (mindful of currency and access issues).

Control expenses, build an emergency buffer.

Before you invest heavily, ensure you have a buffer for shocks (job loss, illness, major repairs). Given the economic unpredictability, that buffer gives you the freedom to invest without being forced to liquidate at the wrong time.

Keep learning and adapting.

The environment will shift: changes in tax law, pension system reforms, capital market access, inflation rates, currency pressures. Stay informed. For example, many financial advisers in Trinidad & Tobago emphasize consistency and knowledge building over chasing “get rich quick” schemes.

Align with your risk appetite and timeline.

If you are early in your career, you may take more risk and favour growth assets; if you are near retirement, you may favour more stable income-generating assets. Tailor your approach rather than copying someone else’s plan.

Minister Tancoo’s message is a timely wake-up call: relying solely on the NIS (or any one system) for building wealth is increasingly risky, especially in the current socio-economic context of Trinidad and Tobago. That does not mean the NIS is useless: it still provides value and should be part of a broader context of financial planning. But it means you should take responsibility for your financial future, build habits, diversify, and adapt.

You already have strong entrepreneurial acumen and a business development mindset. Apply those same skills to your personal financial journey: set clear targets, treat your savings like a business income stream, evaluate risk and return, monitor performance, and adapt as the landscape changes.

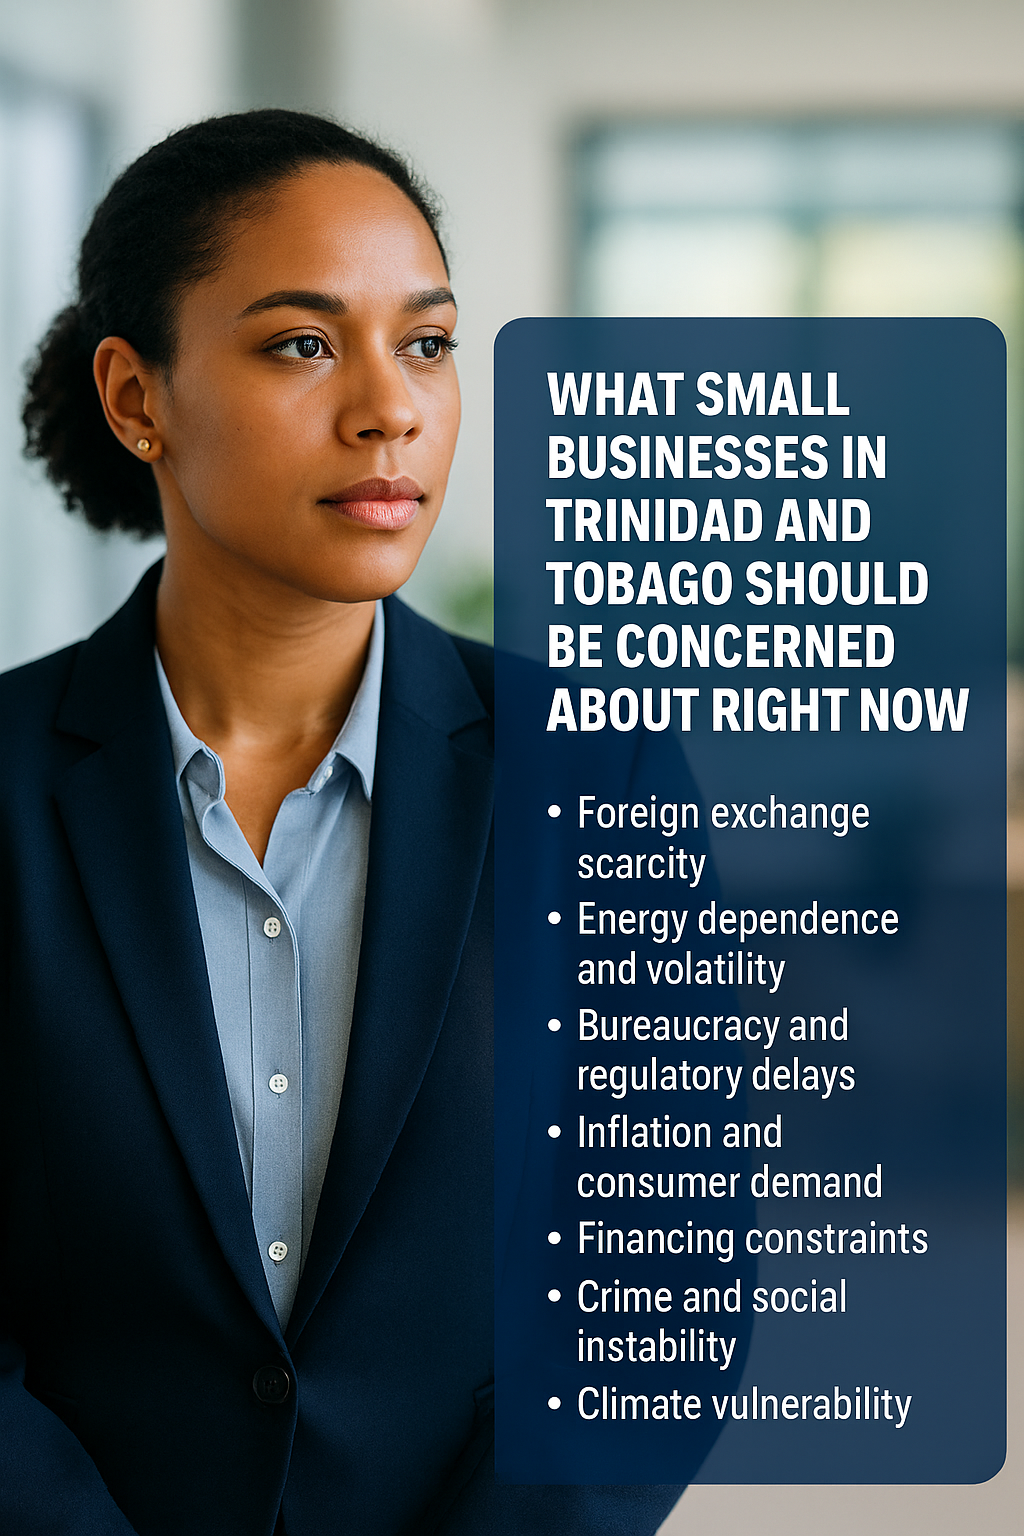
What Small Businesses in Trinidad and Tobago Should Be Concerned About Right Now

Running a small business in Trinidad and Tobago has never been easy, but 2025 has brought a unique mix of economic, political, and social shifts that are making the environment even more challenging. While the entrepreneurial spirit remains strong across the country, small businesses need to approach the next 12 to 18 months with sharper awareness, stronger risk management, and more adaptive thinking. As an economist watching regional trends closely, here’s what I believe every small business owner in Trinidad and Tobago should be paying attention to right now.

Foreign Exchange Scarcity and Cost Pressures

One of the most immediate and frustrating realities for small businesses is the ongoing shortage of foreign exchange. Accessing U.S. dollars and other foreign currencies is increasingly difficult, with many businesses waiting weeks or months for allocations. Banks actually have businesses on a waiting list, and not just for U.S. dollars, but even Euros as well. This delay forces some to resort to the parallel market, where exchange rates are significantly higher, eroding already thin profit margins.

For businesses that rely on imported goods, raw materials, or equipment, this poses a serious risk. Cost planning becomes unpredictable, pricing strategies are harder to maintain, and in some cases, operations can be disrupted entirely. Companies should be exploring alternative sourcing options, negotiating more flexible supplier terms, or holding higher inventory levels if cash flow allows.

Energy Dependence and Macroeconomic Volatility

Trinidad and Tobago’s economy remains heavily tied to the energy sector. Oil, gas, and petrochemicals still account for a large share of GDP and export earnings. While the sector continues to generate revenue, it also exposes the country to external shocks. Fluctuations in global energy prices, production disruptions, or changes in global demand can all ripple into slower economic growth, tighter public finances, and weaker domestic demand.

For small businesses, this means heightened uncertainty. Government spending, consumer spending power, and business confidence are all linked to the fortunes of the energy sector. The pace of economic diversification remains slow, so businesses should anticipate cyclical ups and downs and plan accordingly.

Bureaucracy, Regulation, and Business Friction

Despite efforts to improve the business environment, regulatory delays, bureaucratic red tape, and inconsistent enforcement continue to frustrate small business owners. Licensing, permits, and tax compliance processes remain slow and often unpredictable. Legal disputes can take years to resolve, and government procurement processes are still viewed as opaque and overly complex.

This environment raises costs, lengthens lead times, and makes growth planning more difficult. Small businesses should build realistic timeframes into their operations, ensure they are fully compliant, and consider collaborating with business associations to advocate for regulatory reform.

Inflation, Consumer Spending, and Cost of Living Pressures

Inflation remains a real concern, especially when combined with foreign exchange challenges. Even with relatively moderate headline inflation, the cost of imported goods continues to climb. At the same time, rising food prices and cost-of-living pressures are eating into household budgets.

For many consumers, non-essential spending is the first to go. Businesses in retail, services, and lifestyle sectors may feel the pinch as demand softens. To stay resilient, small businesses should focus on value-driven offerings, flexible pricing strategies, and products or services that remain relevant even in tighter economic conditions.

Financing Constraints and Higher Credit Risk

Access to finance has always been a challenge for small businesses, and the current environment may tighten lending conditions further. Banks are likely to remain cautious, especially with weaker consumer demand and slower economic growth. For entrepreneurs without strong collateral or a solid credit history, accessing loans for growth or even working capital can be difficult.

Now is the time to strengthen financial records, improve cash flow management, and explore alternative financing models such as supplier credit, co-operative lending, or investment partnerships.

Policy Shifts and Fiscal Pressures

The recent change in government introduces another layer of uncertainty. Policy priorities, tax measures, and regulatory approaches could all shift as the new administration seeks to address fiscal pressures and social demands. With public debt rising and revenue challenges persisting, there is a real possibility of new taxes, reduced subsidies, or increased enforcement.

Small businesses must stay alert to policy announcements, budget statements, and legislative changes. Being proactive rather than reactive can help you adjust your business model ahead of regulatory changes rather than scrambling after the fact.

Crime, Security, and Social Instability

Rising crime rates continue to affect both the cost and safety of doing business. Security systems, insurance premiums, and operational risks all add to the expense of running a small enterprise. Beyond that, protests linked to economic frustration or service delivery can also disrupt transportation, supply chains, and customer traffic.

Factoring security into your cost structure and continuity planning is no longer optional. It’s essential!

Climate Vulnerability and Infrastructure Gaps

Finally, climate-related risks and infrastructure limitations should not be ignored. Severe weather events, flooding, and drainage issues can disrupt operations or damage assets, particularly for businesses in manufacturing, logistics, or retail. Weak infrastructure, such as inadequate roads or unreliable utilities, also adds hidden costs.

Businesses should assess their physical vulnerabilities, insure critical assets, and develop contingency plans for disruptions.

What Small Businesses Can Do Now

While these challenges are significant, they’re not insurmountable. Small businesses that adapt early and plan strategically can still thrive. Here are a few practical steps:

  • Conduct stress tests on your cash flow to see how you’d manage under cost increases, supply delays, or reduced sales.
  • Diversify your revenue streams to avoid relying too heavily on one market or product.
  • Build local supplier relationships and explore nearshore sourcing to reduce foreign exchange exposure.
  • Manage debt conservatively and avoid overleveraging in uncertain times.
  • Monitor government policy closely and adjust your business plans quickly when changes occur.
  • Strengthen collaboration with industry associations to amplify your voice on policy issues.

The road ahead for small businesses in Trinidad and Tobago is not without obstacles, but it’s also full of opportunity for those who are agile, informed, and prepared. The current state of affairs demands more than just optimism; it calls for strategic action, sound financial management, and a deep understanding of the forces shaping the economy. With the right approach, small businesses can continue to be the engine of growth and innovation that the country needs.

WHO FILES A TAX RETURN

  • Sole traders & self-employed persons – even if you made little to no income in the year.
  • Registered companies – whether you are profitable or not.
  • Individuals with additional income sources outside of employment.
  • Partnerships – Green Fund Levy

TAX RETURN VS ANNUAL RETURN


Running a business is more than just keeping customers happy and managing sales. Behind the scenes, there are compliance requirements legal and financial obligations you must meet every year to stay in good standing.

In Trinidad and Tobago, two of the most common (and often misunderstood) requirements are the Tax Return and the Annual Return. While they sound similar, they have different purposes, different deadlines, and different filing authorities. Missing either one can cost your business dearly.

This guide will walk you through what they are, why they matter, and how to make sure you stay compliant.

Understanding the Tax Return

A Tax Return is your formal report to the Board of Inland Revenue Division (BIR) that details your income, expenses, and the amount of tax you owe for a given financial period.

It is the government’s way of ensuring that individuals and businesses are paying their fair share of taxes based on actual earnings.

Who Files a Tax Return?

  • Sole traders & self-employed persons – even if you made little to no income in the year.
  • Registered companies – whether you are profitable or not.
  • Individuals with additional income sources outside of employment (such as rental income or investments).
  • Partnerships – Green Fund Levy. Note that individual partners pay Income Tax (something entirely different), while the Partnership itself pays Green Fund Levy.

When is it Due?

  • Sole traders & individuals: Usually April 30 each year for the previous year’s earnings.
  • Companies: Tax Returns must be submitted before October 31st of the following year, while payments must be made before April 30 of this same year in order to avoid penalties.

What’s Included in a Tax Return?

  • Total revenue earned.
  • Operating expenses (rent, salaries, utilities, etc.).
  • Profit or loss for the year.
  • Tax payable or refund due.

Key Point:

The Tax Return focuses on financial performance, your numbers, not your company’s legal status.

Understanding the Annual Return

An Annual Return is not about your income or expenses; it’s about your company’s structure and legal details.

It is filed with the Companies Registry to confirm your company’s current status, such as who owns it, who manages it, and how shares are distributed.

Who Files an Annual Return?

  • All registered companies in Trinidad and Tobago (limited liability), regardless of whether they are actively trading or not. As of recent (October 2024), partnerships, non-profit organisations and non-profit companies also have to file.
  • Not required for sole traders.

When is it Due?

  • Every year on the anniversary of your incorporation date for companies and registration date for partnerships.

What’s Included in an Annual Return?

  • Company name and registration number.
  • Details of directors and shareholders.
  • Share capital information.
  • Registered office address.
  • Any loans or charges in the name of the company

Key Point:

The Annual Return is about providing updates to the Companies Registry about the current status of your business. In other words, they want to know who are your current directors, your current secretary, if your business has changed location from the one last reported, if you issued any new shares, etc.

The Consequences of Missing Deadlines

Filing late, or not filing at all can have serious consequences:

  • For Tax Returns: Late fees, interest on unpaid taxes, audits, and legal action.
  • For Annual Returns: Fines, loss of good standing, and possible removal (“striking off”) from the Companies Register.

Many business owners mistakenly think that if they file one return, they are covered for both. Unfortunately, that’s not true, these are separate legal obligations.

A Side-by-Side Comparison


Tax Return

Annual Return

Filed With Board of Inland Revenue (BIR) Companies Registry
Purpose Reports income, expenses, and tax liability

Updates the Companies registry with company ownership, directors, and structure

Focus Financial performance Legal standing
Who Files Sole traders, registered companies, self-employed individuals, partners file Income Tax Companies only, partnerships, non-profit organisations and non-profit companies
Deadline April 30 for individuals; Oct 31 for companies Anniversary of incorporation

(See notes above for detailed clarification)

Best Practices to Stay Compliant

Track Your Dates – Mark both deadlines on your calendar to avoid late filing fees.

Keep Records Year-Round – Store receipts, invoices, and contracts so reporting is easier.

Work With Professionals – Accountants and corporate secretaries can help prepare and file on time.

File Even if Inactive – If you earned nothing or made a loss, you still must file to remain compliant.

Plan Ahead – Don’t wait until the last minute; gather your information early           

Final Word                                                        

The Tax Return and the Annual Return are both essential for keeping your business healthy in Trinidad and Tobago. One ensures that you’re meeting your tax obligations, the other ensures your company remains legally recognized.

At The Timely Entrepreneur Resource & Research Centre, we’ve seen too many businesses face unnecessary fines or lose their legal standing simply because they didn’t understand the difference.

Knowledge is protection and in business, protection means profitability.

Need Help Filing?
We can guide you step-by-step, prepare the required documents, and ensure you meet every deadline without stress.

The Timely Entrepreneur Resource & Research Centre – Helping entrepreneurs in T&T start, manage, and grow the right way. If you need further clarification, please call our Compliance department @ 868 760-6221.

Stop Trading Time for Money: How to Build Passive Income from the Business You Already Have

When Your Business Needs to Work Without You

Entrepreneurs often reach a point where the daily hustle becomes unsustainable. You’re the first one in and the last one out. You wear every hat: manager, marketer, service provider, and sometimes even janitor. And while you’re building your business with heart and purpose, you do understand that if your income stops when you stop, your business is not truly sustainable.

One of the most powerful things we teach at The Timely Entrepreneur Resource and Research Centre is how to create passive or semi-passive income from the very business you already own. This isn’t about starting something new, but it’s about looking at what’s already in your hands and finding ways to multiply its impact without multiplying your hours.

Let’s look at how this can work for real Caribbean business owners across various industries.

What Is Passive Income Really?

Passive income doesn’t mean you never have to work again. Instead, it means that with the right systems in place like automation, digital products, or recurring revenue models, your business can generate income without needing you to be constantly present or available.

The goal? To reduce dependency on you as the owner and give you back time, energy, and freedom while still earning.

Real-World Examples by Industry

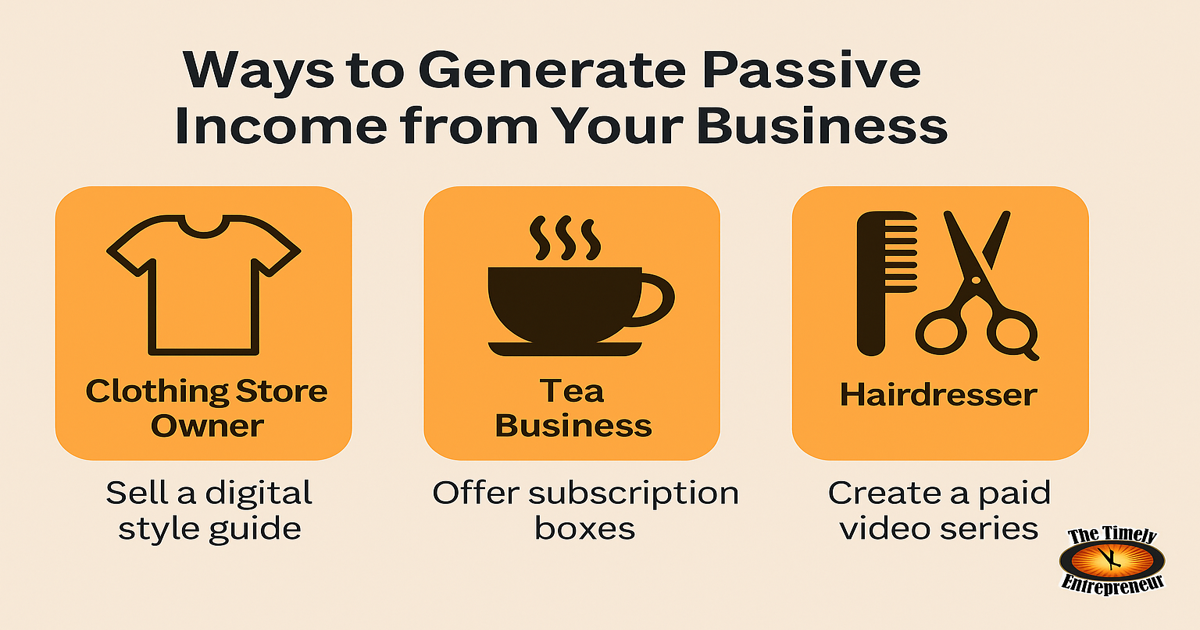
Clothing Store Owner

Instead of relying solely on in-store sales, create a mini digital style guide such as “How to Dress for Your Body Type” and sell it online. Set up an e-commerce site that offers curated outfit bundles by occasion (workwear, weekend casual, etc.) and offer automatic reordering for loyal customers.

Tea Business

Use your knowledge of herbs and wellness to create a downloadable e-book or a paid “Tea & Wellness” workshop. Offer subscription boxes where customers receive a curated tea blend every month without needing to reorder each time.

Hairdresser

Turn your expertise into a video series or a paid online course. For example, “Protective Styles 101” or “Healthy Hair at Home.” Sell hair care kits with your recommended products. Clients can continue learning from you and buying from you even when you’re not in the salon.

Construction Company

Create downloadable resources or recorded webinars on topics like “How to Budget for Your First Renovation” or “Top 5 Ways to Prepare Your Home for Construction.” You can also sell toolkits or checklists for home maintenance that clients can purchase year-round.

Tuition Centre

Record your most popular lessons or exam prep sessions and offer them through an online learning portal. Build a membership model where students gain access to recorded content, quizzes, and bonus resources for a monthly fee.  No live teaching required every week.

Mini Mart Owner

Introduce weekly grocery subscription bundles or digital ordering for routine household items. Partner with local vendors to create themed “Survival Kits,” “Snack Boxes,” or “Local Favourites Packs,” with delivery included.

Catering Business

Sell meal prep guides, downloadable recipe e-books, or pre-recorded cooking classes. You can also create meal kits that customers can assemble themselves, with ingredients and instructions included.

Fitness Trainer

Offer recorded workout programs, meal plans, and wellness challenges as part of a paid online membership. Build a fitness app or downloadable guide that doesn’t require live coaching.

Photography Business

Sell presets, editing guides, or “how-to” courses for amateur photographers. You can also license your images to online stock photo sites for recurring royalty income.

It’s Not About Doing More

Many entrepreneurs assume that earning more means working more. But the truth is, passive income requires you to work differently. It means setting up products, services, and systems that continue to add value without your constant presence.

You don’t need to be everywhere at once. You just need to build once with intention and design your business to grow even when you’re not looking.

If you’re tired of running full speed just to stay afloat, it may be time to create income that doesn’t always need your hustle to survive.

🔸 Are you ready to explore what passive income looks like for your specific business? Let us help you map it out.

🔸 Click the link to book a BIT Session for urgent support with your next step.


BUSINESS IN TROUBLE ?

Pay Yourself as an Entrepreneur!

Let’s get honest:
Too many small business owners are making sales but not taking home a cent for themselves. They’re covering all expenses: paying rent, covering suppliers and even spending on Facebook ads. But when it’s all said and done, they’re left empty. You’ve got to pay yourself as an entrepreneur!

What no one tells you is this:

If you don’t build your business in a way to pay yourself, your business will never truly work for you. And eventually, you’ll burn out, be frustrated and financially stressed, wondering where all the money went.

But how can you pay yourself when sales are low or inconsistent?

Let’s break this down. Here are some ways The Timely Entrepreneur worked out:

Shift Your Mindset First

Stop treating your salary as a reward. A salary is not something you earn only if things go well. It’s a non-negotiable business expense just like internet bills, inventory or accounting fees. So, if your business has a monthly operating budget, your pay must be included in it even if it’s small. If it’s not in the budget, then you’ve built your business model wrong!

Pay Yourself a Percentage, not a Fixed Amount

When revenue is low or inconsistent, we understand that a fixed salary can be stressful. Instead, pay yourself a percentage of net revenue or profit.

For Example: If your business earns $8,000 this month, and your fixed expenses are $5,000, you’re left with $3,000.
Choose a percentage, let’s say, 30% of net profit and pay yourself $900.
This leaves room for reinvestment while still honouring your role in the business.

Pro tip: Choose a percentage that aligns with your goals (10% if you’re reinvesting heavily, 30–50% if it’s your main income).

But what if the business owns less than $5000 TT per month? How can one pay one’s self a salary from that?

Now that’s a very real situation and one that many small businesses face.

If your business earns less than $5,000 TT per month, you can still pay yourself a salary, but it requires intentional structure, discipline, and understanding of your business priorities.

Here’s how it can be done realistically:

Shift from “Salary” to “Owner’s Draw” Temporarily – Open a Separate Business Account & “Owner Pay” Account

Whether you’re a sole trader, company or other business structure, set up 2 accounts:

  • Business Account for all income and expenses
  • Owner Pay Account where your salary is transferred monthly or biweekly

Why? Because when all your business money is mixed with personal expenses, it’s easy to “borrow” from yourself and lose track. This system helps build discipline.

Instead of thinking in terms of a formal salary (like in a job), think of it as an owner’s draw – a small, planned amount you take out every week or month from what’s available after expenses.

Example:
If you earn $4,800 TT/month and your bare minimum business expenses (inventory, data, delivery, etc.) are $3,000:
→ That leaves you with $1,800 TT.
→ Decide to give yourself a set draw of maybe $1,000, and keep the remaining $800 for savings or reinvestment.

If you use the percentage rule to stay consistent, simply choose a fixed percentage, no matter how small. 10%–20% of total revenue is a good place to start. If your sales fluctuate:

“This month I made $3,500, I’ll still pay myself 15%, which is $525. Next month might be higher or lower, but stay consistent in percentage, not amount.”

This teaches you to think like a disciplined business owner, even at low-income levels.

Build Your Pay into Your Pricing

Ask yourself: “Is my current pricing too low to ever support me?”

If your profit per sale is only $10 or $20, you’ll need to sell 100+ items per month just to pay yourself. That’s not sustainable.

Even when you’re starting small, build your pay into your cost formula:

Selling Price = Cost of Product + Expenses + Your Pay + Profit Margin

If you pay yourself just $100 per week now, design your pricing around that goal.

If you can’t afford to pay yourself based on your current pricing, maybe you’re undercharging.

  • Are your prices based on actual cost + value?
  • Are you accounting for your labour, creativity, and time?

Your salary must be a line item in your cost structure.
Even if you’re not a limited company, you are still the engine behind it all. Don’t price yourself out of your own business.

Use the Profit First Model (Simplified)

Consider this simplified system:

Every time you get paid:

  • 50% → business expenses
  • 30% → owner salary
  • 10% → taxes
  • 10% → savings/reinvestment

Adjust based on your stage, but the idea is to put money where it matters most — not where it simply disappears.

Manage Personal Expenses with Intention

Yes, this may mean that you have to cut personal costs to make it work. This part is tough, but necessary. If you are drawing $1,000–$1,500 TT/month from the business, then your personal expenses must be minimal. Your personal budget has to reflect that reality.

This might mean:

  • Delaying luxuries
  • Cutting unnecessary subscriptions
  • Getting creative with meals and transportation
  • Staying with family while you build

This sacrifice will just be temporary, don’t worry. Discipline now creates freedom later.

Set a Minimum Survival Salary

Calculate what’s the least you need to survive personally each month (food, transport, phone credit, etc.). Let’s say it’s $1,200 TT.

If your business can’t make room for at least that, then:

  • You either need to increase sales
  • Or reduce business costs
  • Or diversify income (side hustle, part-time work, etc.)

Consider Paying Weekly, Not Monthly

It’s often easier to manage small amounts weekly. For Example: If you only earn $4,000 TT/month, pay yourself $250–$300/week consistently. It feels more manageable and ensures you’re not always “waiting on month-end” to eat or live.

Track EVERYTHING.

The truth is in the numbers. Track:

  • Every dollar you earn
  • Every expense
  • What you pay yourself
  • What’s left behind

This builds self-awareness and helps you see what’s realistic and where changes are needed.

If your business can pay everyone and everything else but not you, it’s time to re-evaluate.

As Entrepreneurs, we need to hold ourselves accountable for what goes on in our businesses. We need to develop discipline in our spending, in our pricing, and in how we manage our most liquid asset, cash, because if we keep building businesses that starve the builder, we’re only building resentment, and that’s not why you started your business. You don’t wait to start paying yourself after your business gets big. You pay yourself so that your business has something to grow you into.

Have you started paying yourself yet, or are you still trying to figure it out? Check out our Business in Trouble Sessions and reach out to us for all your business needs.